Quick answer
Compare the raise you received with the costs that changed
Compare what actually reached your account with what your costs did after the raise. Often part went to higher essentials, part to new commitments, and only a little was left. Give the rest a job before new monthly bills quietly take it.
Find the amount that actually reached you
Compare two representative payslips and the corresponding deposits. Separate a permanent increase from overtime, a one-off bonus, or an expense reimbursement. Check deductions and payroll changes rather than assuming the gross increase is available to spend.
Ask payroll or a qualified local adviser if a payslip does not make sense.
If your income varies, compare several ordinary months rather than the highest payment before and after the raise. An unusually good month can make a new ongoing expense seem easier to afford than it is.
Sort the increase into three places
- More expensive essentials: the same necessary items now cost more.
- Changed responsibilities: care, travel, housing, or repayments genuinely changed.
- Upgrades and convenience: things you chose because the raise seemed to create room.
The US Federal Reserve's report on household financial well-being in 2025 identifies prices as a major financial concern among its US respondents. Your own bills are better evidence than any survey.
Use your own bills for that evidence. Compare quantities as well as totals: a larger grocery bill may reflect higher prices, more people at home, more purchases, or some combination.
See what is actually left of the raise
| Change | Amount |
|---|---|
| Extra take-home pay | 8,000 |
| Higher housing and utility costs | 3,000 |
| New necessary travel cost | 1,500 |
| New optional recurring payments | 2,000 |
| Uncommitted increase | 1,500 |
In this example, the household did not gain 8,000 of freely spendable money. It gained 1,500 after the listed changes. Some commitments might be adjustable; others may not be.
Start with recurring choices because they affect future months too. An unused upgrade is a clearer candidate than a necessary journey. Check cancellation fees and whether a cheaper alternative actually meets your needs.
- Compare your income for a month before and after the raise.
- Check Recurring Expenses for new monthly payments that crept in.
- Compare spending by category across those months in Insights.
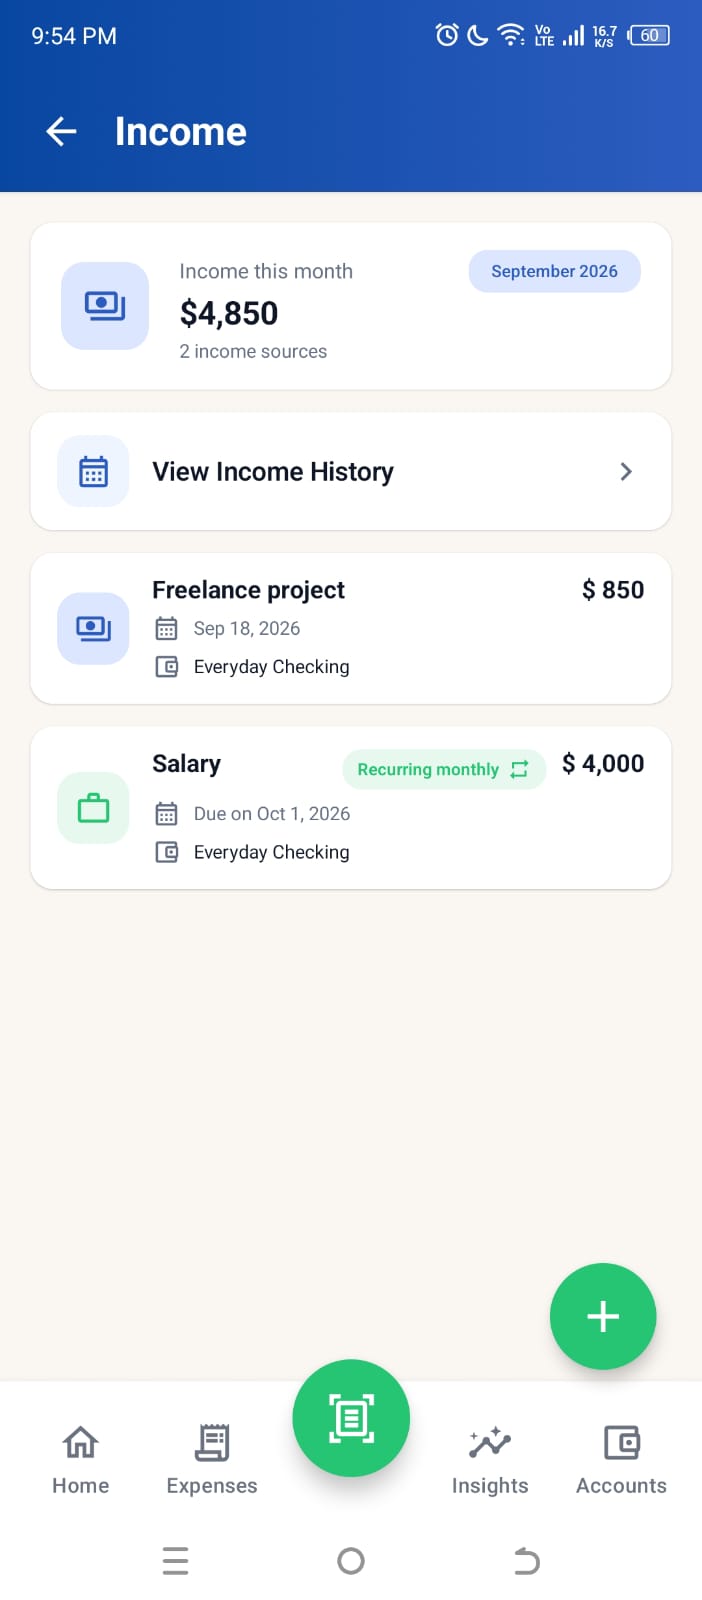
Screen shows sample data.
Give the next increase a job before it disappears
Choose a purpose for the part that remains: rebuilding a reserve, reducing a costly debt, making room for an enjoyable purchase, or a combination. You do not have to save every bit of a raise for it to improve your life.
Decide on ongoing upgrades only after seeing a normal month at the new income. A recurring payment continues after the excitement of the raise has passed.
If the entire increase went to essential costs, recognize what it achieved: it may have prevented a deeper shortfall. That is different from getting ahead, but it is not failure. Review the remaining gap honestly instead of treating every financial problem as a lack of discipline.
Written with AI assistance by Higxel Editorial. Example figures are made up to show the method; this is general information, not financial advice. Sources checked September 12, 2026. Some sources describe one country; local rules and costs differ.
Sources