Quick answer
Start with the next payday, not the calendar month
Before you spend anything, set aside what's needed until your next payday, including bills that haven't arrived yet. What's left, not your bank balance, is your spending money. If essentials cost more than you earn, a tighter allowance won't fix it; that's an income gap and needs a different plan.
Three problems that can look exactly the same
- A timing problem: income covers the month, but several bills arrive before the next payment.
- A missing-cost problem: the plan covers rent and groceries but forgets school costs, medicine, repairs, gifts, or annual fees.
- An income problem: housing, food, transport, care, and required payments already use more than you earn.
Look at your last complete pay cycle. Start with the amount that actually reached your account. List payments made, cash withdrawn, and obligations still outstanding. Cash withdrawals need another look: taking money out is not the same as knowing where it went.
Do not count a transfer between your own accounts as a new expense. If you count card purchases as spending, avoid counting the same purchases again when you pay the card bill. Existing debt payments still need a place in your cash-flow plan.
Work out a spendable balance
Here's how one pay cycle can look:
| Money coming in or committed | Amount |
|---|---|
| Take-home pay | 50,000 |
| Housing, utilities, transport, and required payments | 32,000 |
| Known irregular costs due this cycle | 3,000 |
| Small contingency reserve | 1,000 |
| Left for food and other everyday spending | 14,000 |
If there are four weeks until payday, that leaves 3,500 a week. If there are five, it leaves 2,800. The number is only useful if it can cover your real needs. If food and other necessities cost more, revisit the plan instead of pretending the allowance is achievable.
You do not need several bank accounts to do this. A written list of reserved amounts is enough, provided you check it before spending.
- Set a monthly budget.
- Record spending as you go: a receipt photo, your voice, or a quick entry.
- Home shows how much is left and how much you can spend each day for the rest of the month.
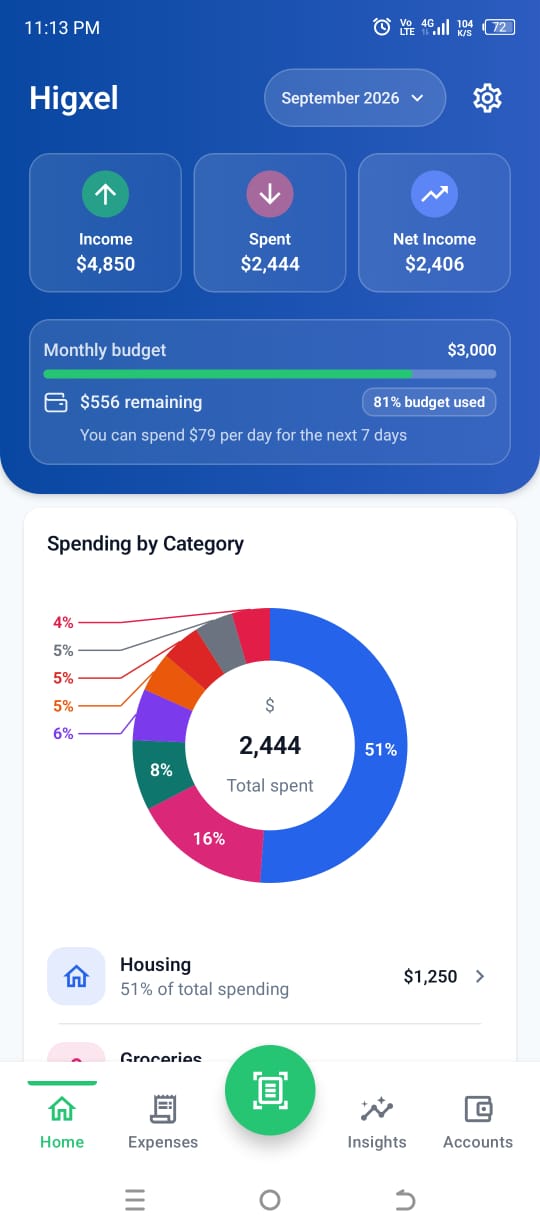
Screen shows sample data.
Put due dates beside the amounts
A monthly total hides the day you run short. Write each income date and bill date on one calendar. The CFPB's bill-planning guidance explains how a bill calendar can help you see what is due and when.
If timing is the problem, ask the provider whether a due-date change is possible. Check whether the change creates a longer first billing period, a fee, or another payment. Wait for written confirmation before relying on the new date.
For predictable but infrequent expenses, divide the expected cost by the pay cycles remaining before it is due. That gives you a saving target for that particular bill, rather than a vague promise to handle it later.
Make one useful change this payday
Choose the biggest explainable mismatch. It might be an unaffordable recurring commitment, a bill date, or several purchases missing from your plan. Fixing that mismatch is more useful than banning every small pleasure.
If your essentials exceed your income, protect food, safe housing, health, and necessary transport. Contact creditors or a reputable local money-advice service early about payments you cannot meet; consequences and available support differ by country.
After a week, compare what you expected with what happened. Adjust an unrealistic category. A budget should tell you the truth, not give you another reason to feel guilty.
Written with AI assistance by Higxel Editorial. Example figures are made up to show the method; this is general information, not financial advice. Sources checked September 12, 2026. Some sources describe one country; local rules and costs differ.
Sources