Quick answer
Build the plan around a cautious income figure
Build your budget on a low, normal month, not your best one. Cover essentials from that baseline, keep a buffer for slow months, and give any extra money a job in a fixed order: taxes and work costs, upcoming bills, the buffer, then everything else.
Find your baseline income
Look at what actually arrived in each of the last six months. Here is one example:
| Month | Income received |
|---|---|
| A | 28,000 |
| B | 41,000 |
| C | 22,000 |
| D | 36,000 |
| E | 50,000 |
| F | 25,000 |
The average is about 33,667, but budgeting on the average leaves you short in half the months. A safer baseline is the average of your three lowest normal months: (22,000 + 25,000 + 28,000) ÷ 3 = 25,000. Leave out one-off payments, like an unusually large project, when you pick them.
Make essentials fit the baseline
List housing, utilities, basic food, necessary transport, care, and required payments. Add essential business costs if you work for yourself, keeping the business and household figures separate. This is your floor, not the life you're aiming for.
Look back over enough months to see quiet periods and seasonal changes. MoneyHelper's irregular-income guidance recommends a cautious baseline rather than assuming every month will be a good one.
If you are newly self-employed, a long history may not exist. Use confirmed work, realistic collection dates, and a smaller spending commitment while you learn the pattern. Mark uncertain payments as uncertain.
If essentials cost 23,000 and your baseline is 25,000, you have 2,000 of room in a lean month.
Build a buffer for slow months
A common target is one to three months of essentials, here 23,000 to 69,000. Start with one month, and fill it from good months, not lean ones. A buffer is what lets a late payment be an inconvenience instead of a crisis.
Plan the gap between earning and getting paid
Put expected payment dates and bill dates on the same calendar. A month can be profitable overall and still leave you short in the middle. Check what happens if your largest expected payment arrives late.
| Item | Amount | Timing |
|---|---|---|
| Cash available now | 12,000 | Today |
| Essential bills due | 18,000 | Before the 10th |
| Expected client payment | 15,000 | Around the 20th |
The immediate gap is 6,000, even though the expected payment could cover it later. Knowing this early gives you time to follow up on payment, discuss arrangements, or adjust a nonessential commitment. If a bill will be late, call the provider before the due date.
Give extra income an order of jobs
When a larger payment arrives, decide what it needs to cover before treating it as a windfall:
- Costs of earning that income and any required tax provision.
- Essential bills and required payments coming up next.
- A reserve for a weaker period.
- Other goals and optional spending, if money remains.
Tax rules depend on where you live and how you work. Ask your tax authority or an accountant how much to set aside from each payment.
Pay yourself a steady amount
Once your buffer covers a month or two, let all income land in one account and move a fixed 25,000 to your spending account each month. Good months top up the buffer; lean months draw from it. Your household gets a steady amount even when your income isn't steady.
- Add each payment as one-time income on the day it arrives, not when you invoice.
- Mark steady income, like a retainer, as recurring.
- Compare income with spending on Home each month.
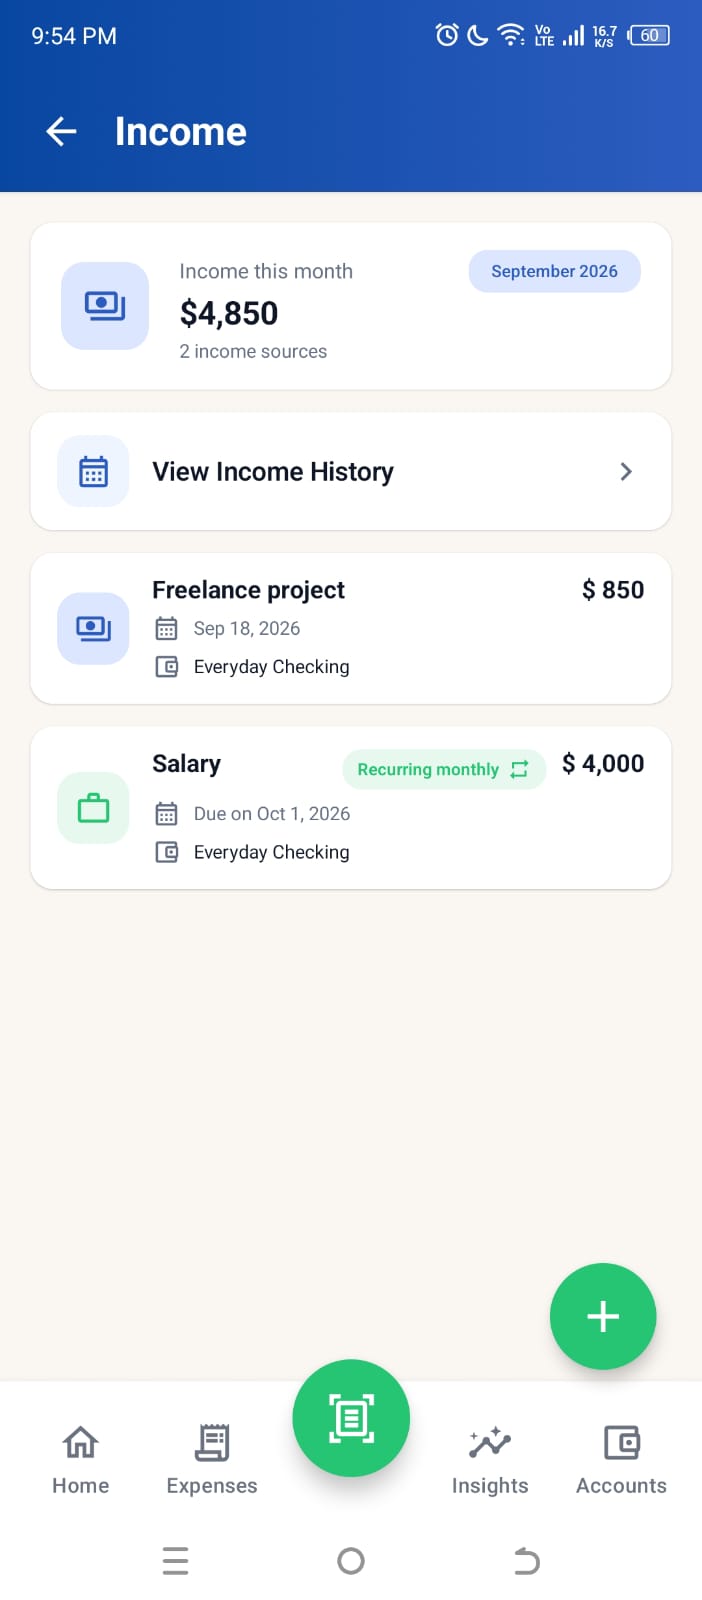
Screen shows sample data.
Use two versions of the month
Make a normal plan and a lean plan. The lean version identifies what can wait if a payment is late, without cutting essential care or ignoring serious obligations. Decide this in advance, when you are not under pressure.
Review briefly each week: what arrived, what changed, and what is due before the next likely payment? Update the calendar rather than rebuilding a complex spreadsheet from scratch.
If repeated low months cannot cover your planning floor, the problem is bigger than timing. You may need to revisit prices, hours, costs, work options, or available support. Better record-keeping can reveal the gap, but it cannot create income by itself.
If standard budget percentages do not fit your essential costs, build an honest allocation from the amounts you actually need.
FAQ
Common questions
How much buffer do I need with irregular income?
Start with one month of essentials, then build toward three if your income swings a lot.
Should I budget weekly or monthly?
Monthly for the plan, weekly for a quick check of what has arrived and what's due.
What if my baseline doesn't cover my essentials?
Then it's an income or cost gap, not a budgeting problem. Look at prices, hours, clients or support rather than tighter categories.
How do I handle taxes on irregular income?
Set aside a share of every payment the day it arrives, in a separate account. Your tax authority or an accountant can tell you the right share.
Written with AI assistance by Higxel Editorial. Example figures are made up to show the method; this is general information, not financial advice. Sources checked September 12, 2026. Some sources describe one country; local rules and costs differ.
Sources