Quick answer
Choose the first problem your fund should solve
Start small: pick one likely emergency, like a repair or a prescription, and save toward that first. Keep the money separate but easy to reach. Grow it in stages, and when you use it, that's the fund doing its job.
Separate emergencies from bills you can predict
An emergency fund is for an urgent, unplanned cost or an interruption to income. The CFPB's emergency-fund guidance describes it as a reserve for financial shocks and explains that the appropriate amount depends on your circumstances.
An annual fee or a known school payment is different: you may not pay it monthly, but it is not a surprise. Give predictable costs their own small saving plan if you can. Otherwise they will repeatedly empty the money you meant for emergencies.
Ask two questions before using the reserve: does this need attention before normal income can cover it, and what would happen if I waited? A work-critical repair may qualify; a sale ending tonight usually does not.
Build in stages instead of chasing one huge number
- First cushion: enough for one smaller urgent cost that is relevant to your life.
- Next milestone: enough for a short period of essential spending.
- Longer protection: a reserve based on income stability, dependants, health needs, and reliable support available to you.
There is no single amount that is right for every household. Someone with unpredictable income or dependants may need a different buffer from someone with stable pay and fewer commitments.
If your first target is 2,000 and you can safely save 200 per pay cycle, you'll get there in ten cycles. If 200 makes the rest of the budget fail, choose a lower amount or wait until there is room.
Keep it reachable, but not mixed into spending money
Choose a place where the amount is easy to identify and available when an emergency happens. Check account fees, withdrawal restrictions, and the protection offered in your jurisdiction before opening or using an account.
Keep it somewhere you can reach quickly without losing money, like a savings account, not investments.
A named balance or a separate record can help you avoid spending it accidentally. You do not need a complicated collection of accounts, especially if those accounts introduce extra charges or minimum-balance requirements.
- Add a savings account in Higxel called "Emergency fund".
- Each payday, record a transfer into it; transfers aren't spending.
- Watch it grow in Accounts.
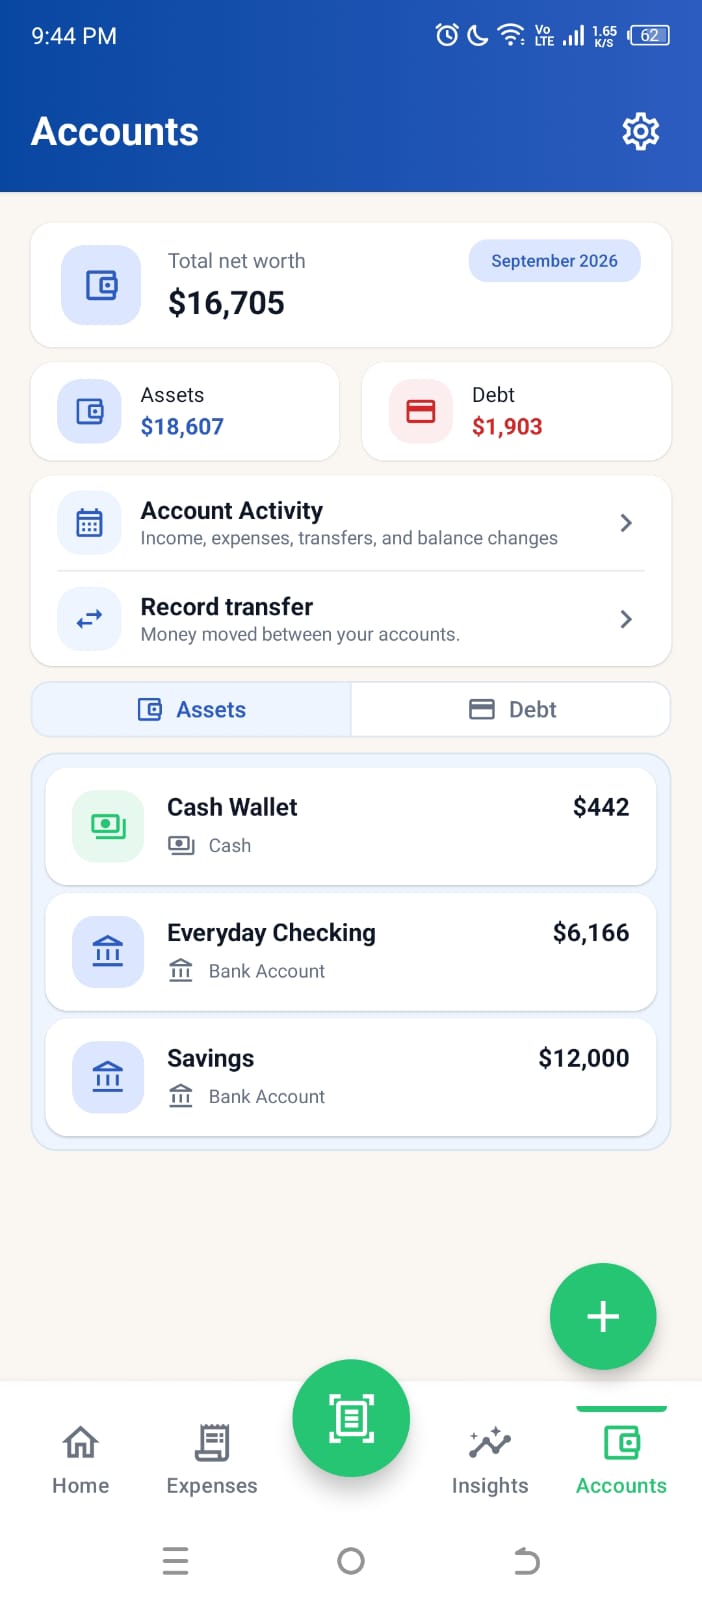
Screen shows sample data.
Make using and rebuilding it part of the plan
If you use the fund for a genuine emergency, it has worked. Once the immediate problem is handled, check how much remains and restart contributions when affordable. Rebuild it from income, not by borrowing.
If you have debt as well, there is a tradeoff between holding a buffer and reducing borrowing costs. Our debt-or-savings article explains what to compare before choosing an order.
If your income does not cover food, safe housing, health, and other necessities, seek available local support before setting a savings target. An emergency fund is a tool, not a test of how disciplined you are.
For a bill you know is coming, a sinking fund can keep the planned cost separate from your emergency money.
Written with AI assistance by Higxel Editorial. Example figures are made up to show the method; this is general information, not financial advice. Sources checked September 12, 2026. Some sources describe one country; local rules and costs differ.
Sources