Quick answer
Start with an amount you can leave alone
First check that something is left after essentials. If it is, save a small amount you won't need to borrow back, even a little each week. If nothing is left, focus on closing the gap or finding support before forcing savings.
Higxel turns receipt photos and voice notes into expenses you review before saving.
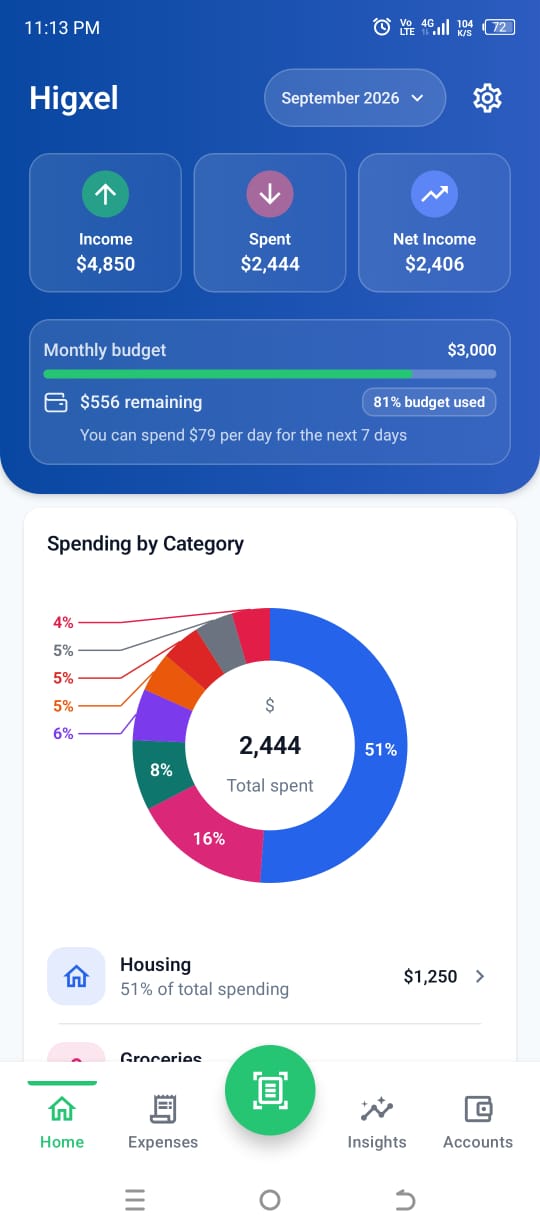
Screen shows sample data.
Separate a tight month from a permanent gap
Write down take-home income and essential spending for one complete pay cycle. Include costs that are easy to leave out: travel to work, prescriptions, household supplies, and care responsibilities. Then add the next predictable irregular bill.
Ask two questions: does income normally cover these costs, and can it cover them before they fall due? If you can afford the month but not the first week, read our payday planning article. If the total does not fit, changing the saving percentage is not the answer.
Support may come from a local benefits program, an employer reimbursement you have not claimed, a lower-cost service, or a payment arrangement. Check the terms before relying on any of them.
Look for savings that do not make life harder
Start with a charge that gives you little value: a duplicate service, an unused subscription, or a repeated avoidable fee. Do not start by cutting medicine, skipping meals, or making your journey to work unsafe.
Compare the full cost of any switch. A cheaper phone plan is not cheaper if leaving the old one triggers a large termination fee. A distant shop may save money on groceries but cost more in travel and time.
Time counts too. Someone working two jobs may reasonably pay for a convenience that makes the week manageable. The question is whether a change leaves you better off overall, not whether it looks frugal on paper.
Try a small, reversible saving routine
- Choose a reason: perhaps the next medicine refill or a small emergency reserve.
- Choose an amount after checking the upcoming bills.
- Move it somewhere separate from everyday spending, while keeping it accessible.
- Review it before the next pay cycle. Reduce or pause it if the transfer would leave essentials unpaid.
Automatic transfers can help when income is predictable, but check balances and account charges first. MoneyHelper's guidance on saving and borrowing highlights why borrowing costs, access to money, and early-repayment charges matter alongside the saving itself.
Saving 100 each week, for example, adds up to 1,200 after twelve weeks, before any fees or interest. Pick a number that fits you, even if it's smaller or irregular.
Using your savings is not always a setback
If you use a small reserve for the emergency it was meant to cover, it has done its job. Rebuild it when there is room. Avoid turning a useful buffer into money you feel forbidden to touch.
For extra income, make the decision when you know the amount: catch up on an essential bill, save a portion, or address an expensive debt. Do not commit a hoped-for bonus before it arrives.
A workable first goal is modest: finish a pay cycle with a little money still available and no new borrowing caused by your saving plan. Once that becomes manageable, increase the amount. You do not have to solve a whole year of finances this week.
Written with AI assistance by Higxel Editorial. Example figures are made up to show the method; this is general information, not financial advice. Sources checked September 12, 2026. Some sources describe one country; local rules and costs differ.
Sources