Quick answer
Look at consequences, not just interest rates
Usually both. Cover essentials and any debt with serious consequences first. Then keep a small emergency buffer so a surprise bill doesn't send you back to borrowing, and put extra money toward your most expensive debt.
Check what happens if you do not pay
A debt with a lower interest rate can still be urgent if nonpayment threatens your housing, an essential service, or an asset needed to work. Legal consequences and the definition of priority debts vary by country.
MoneyHelper's debt-prioritisation guidance explains this distinction in the UK. Use the principle—consider consequences as well as cost—but get local advice about your own obligations.
If you cannot meet essentials and required payments, do not use a generic repayment order to decide which creditor to ignore. Contact the provider and a reputable local debt-advice service early. Ask about available arrangements, charges, and how any agreement affects the account.
Compare the real cost of repayment
Once immediate obligations are covered, list each balance, rate, minimum payment, promotional end date, and early-repayment charge. Check whether an extra payment actually reduces principal and future interest under the agreement.
MoneyHelper's saving-versus-debt guidance notes why expensive borrowing often deserves attention before building large savings, while also considering access to emergency cash and repayment penalties.
For a simplified illustration, a constant 10,000-unit balance costing 24% annually would cost 2,400 over a year; the same amount earning 4% would earn 400 before tax. Real loans may compound, reduce over time, or add fees, so this is not a repayment quote. It shows why a headline savings return alone is not enough to make the decision.
Ask what you would do if a necessary expense arrived
If sending all spare money to debt would force you to borrow again for a small urgent cost, keeping some accessible cash may make the repayment plan more sustainable. Choose a starter amount based on a realistic need, not a universal number from an online rule.
The opposite risk matters too: holding a large sum at a low return while very expensive debt keeps growing. Review the balance rather than deciding that either “all savings” or “all debt” must always be correct.
If you pay down a credit line, you may not be able to borrow that money again. Limits and availability may change. Available credit is not the same as cash you already hold.
Write a plan you can repeat next month
- Protect: essentials and the obligations with the most serious consequences.
- Maintain: required payments, or agreed alternatives if you are in difficulty.
- Reserve: a considered amount for urgent needs, when affordable.
- Direct: the remaining money toward the debt or goal you have chosen after checking the terms.
Revisit the plan when a promotional rate ends, income changes, or the reserve is used. A payment schedule that worked before may need to change.
If you are choosing between debts you cannot afford, dealing with enforcement, or unsure about an agreement, seek qualified local help before making an irreversible payment decision. A short article cannot assess those consequences for you.
Add credit cards and loans as debt in Accounts. Each payment lowers your debt, and your net worth shows the progress.
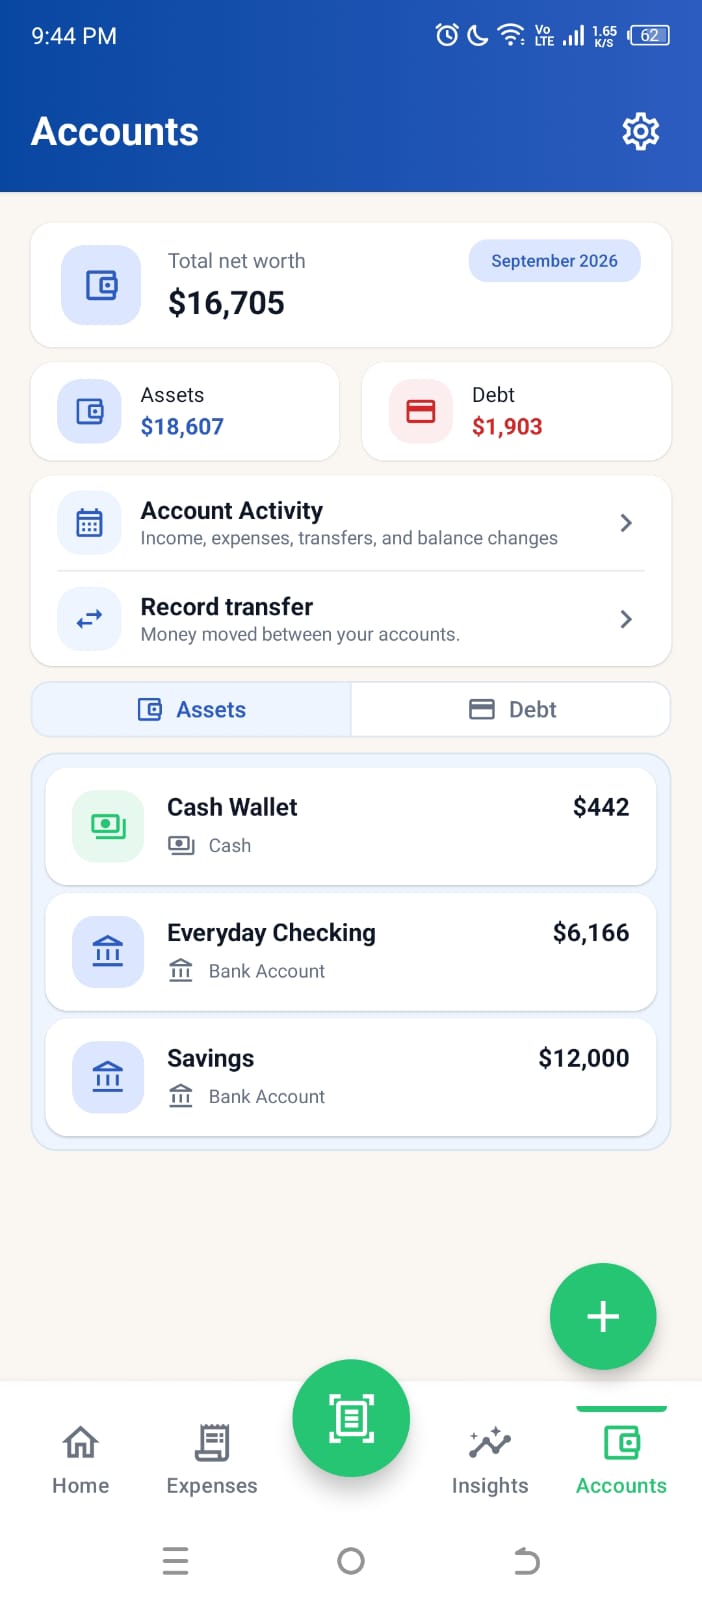
Screen shows sample data.
Written with AI assistance by Higxel Editorial. Example figures are made up to show the method; this is general information, not financial advice. Sources checked September 12, 2026. Some sources describe one country; local rules and costs differ.
Sources